
What Is the Hidden Cost of Financial Inaction?
Oct. 09, 2026
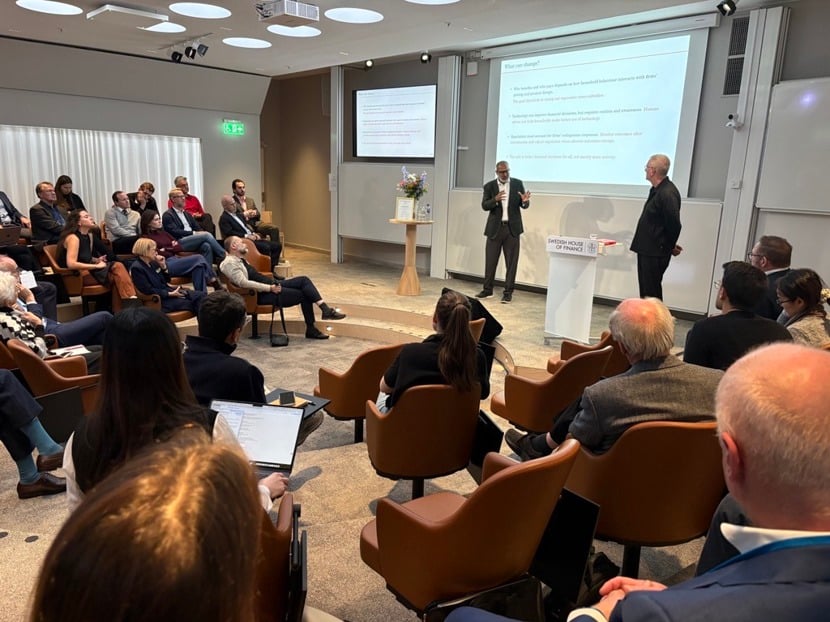
Households can lose substantial sums by failing to refinance, switch insurers, or stay invested through difficult markets. But a fairer financial system must also change how products are designed and how firms respond to consumers, Tarun Ramadorai (LSE) argued at a Swedish House of Finance seminar.
A mortgage left unchanged. An insurance policy renewed without comparison. A financial plan abandoned when markets fall. Everyday decisions can shape household wealth, and the costs are often greatest for those least equipped to navigate the system.
Speaking in Stockholm on October 8, Tarun Ramadorai, Professor of Financial Economics at the London School of Economics and recipient of the 2026 Skandia Research Award on Long-Term Savings, explored who benefits from the financial system, who pays, and what can change.
Drawing on research and his book with John Y. Campbell, Fixed: Why Personal Finance Is Broken and How to Make It Work for Everyone, he argued that household behavior and firms’ responses must be understood together.
When Inaction Becomes a Transfer
In Denmark, homeowners can refinance regardless of their home equity or credit standing, with refinancing costs added to the new mortgage balance. Yet in the research Ramadorai presented, more than half of mortgages had still not been refinanced four years after it became financially worthwhile to do so.
The consequences extend beyond missed savings. In the UK mortgage market, borrowers who repeatedly switch can secure lower introductory rates, while those who fail to refinance move onto higher rates. His research shows how this structure embeds transfers from poorer, less educated households to more responsive borrowers, reinforcing income and regional inequalities.
Inaction also takes different forms. Evidence from housing markets showed owners’ reluctance to sell below their original purchase price, even when waiting carries substantial costs. Reminders may help an inattentive borrower; they may do less for a seller determined to avoid a loss.
When Firms Change the Rules of the Game
Consumer protection can be weakened when firms adapt their products and prices. Ramadorai examined UK motor insurance following rules introduced in January 2022 that prevented renewal quotes from exceeding equivalent new-business quotes.
Insurers reduced introductory discounts and expanded their product menus. Firms with the largest existing customer bases increased their offerings by about 50%. New products could attract customers while older products retained more expensive renewals, leaving substantial gains from shopping around.
The findings highlight the need for regulation to anticipate firms’ responses. Financial education alone also faces limits.
Ramadorai said: “In a way, education has been having a race against complexity in the financial system, and complexity is winning the race at the moment, not education.”
Automation Still Needs Reassurance
Technology can lower costs, simplify comparisons, and automate investment plans. But automation does not remove every need for human support.
In a study of an investment service with automated portfolio management, clients were assigned advisors based on workloads. Advisors with stronger past retention records helped clients remain with the service, particularly when returns were negative. Their value came from ongoing support and reassurance rather than different investment returns.
“Just being with someone who is talking you through the journey keeps you in the journey,” Ramadorai said.
He also warned that technology’s gains can be uneven. More precise credit screening may benefit borrower groups differently, while easier trading can encourage worse decisions. AI guidance offers promise, but whether it provides effective, accessible support remains a research question.
Designing a System That Demands Less
Ramadorai called for clearer product templates, transparent prices, and rules that align advice with customers’ interests. His proposals included automatically refinancing mortgages and a single retirement account that follows workers across jobs.
Ramadorai said: “So our view in the book is households should not need to become experts in every financial product that they use.”
These changes involve tradeoffs. Removing mortgage cross subsidies could mean higher rates for borrowers who currently refinance promptly. Regulators would also need to test designs, monitor firms’ responses, and adjust rules when outcomes fall short.
The goal is better decisions, with the system carrying more of the burden of making them possible.
“I'm not just looking for more activity; it's just better financial decisions that help us across a number of different arenas of household finance,” he concluded.